
Where Does India’s Education Money Go? What CAG Reports Can Tell Us
India spends significant public resources on education through schools, universities, scholarships, infrastructure projects and government programmes. But understanding an education budget requires...
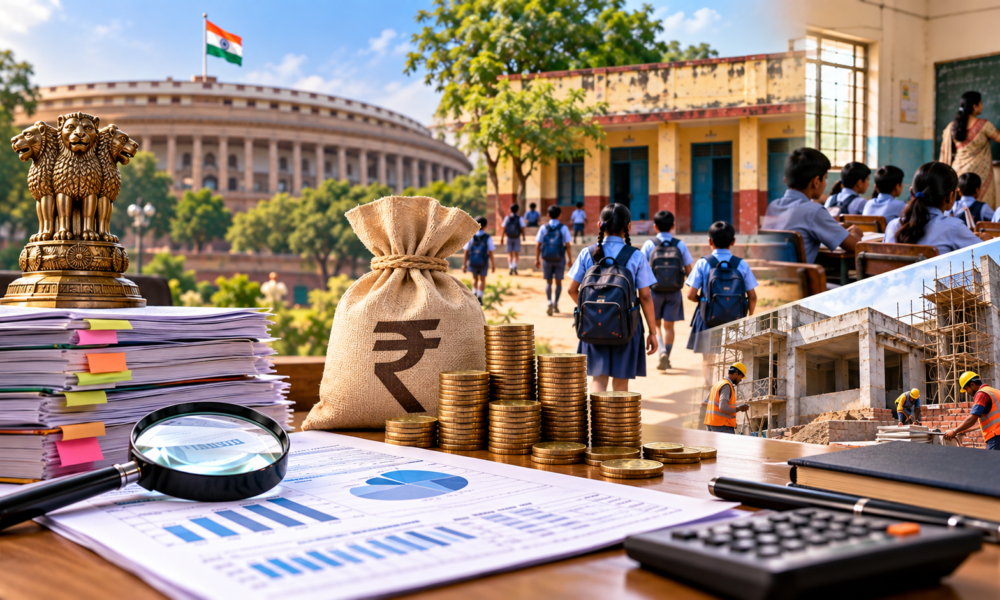
India spends significant public resources on education through schools, universities, scholarships, infrastructure projects and government programmes. But understanding an education budget requires more than looking at the amount allocated. Audit reports can help explain whether funds were planned properly, used for their intended purpose and converted into actual benefits.
The Comptroller and Auditor General of India examines government spending and programme implementation through performance and compliance audits. Its education audit database includes reports on school education and universities, among other areas.
CAG audits can examine the entire chain between a government decision and the intended outcome. This can include planning, release of funds, procurement, construction, staffing, monitoring and actual utilisation.
For example, a school may receive funding for digital infrastructure. The amount allocated may look positive on paper, but an audit can examine whether equipment was purchased, whether it was installed, whether teachers were available and whether students actually used it.
A recent school education audit found cases where ICT facilities were not being used because of a lack of skilled manpower. It also identified a school where an ICT lab and smart classroom were not functional because of the absence of an electricity connection.
This demonstrates the difference between spending money and delivering a public service.
Education expenditure can involve many different areas. Governments may spend on teachers and staff, school buildings, classrooms, laboratories, technology, textbooks, scholarships, training, transport and other programmes. Each area can face different implementation challenges.
Planning is another important part of public spending. A CAG audit of school education recommended better infrastructure assessment and monitoring to ensure projects are completed on time and benefits reach students.
The audit process can therefore identify problems that may otherwise remain hidden in aggregate budget figures.
However, an audit finding should not automatically be interpreted as evidence that an entire education system has failed. CAG reports examine specific programmes, periods, states or samples. Their purpose is to identify deficiencies and recommend corrective action.
For ordinary citizens, these reports provide a way to understand how public education systems work beyond headlines about budgets.
If money is allocated for a laboratory, the relevant question is not only how much was sanctioned. It is whether the laboratory was completed, equipped, staffed and used.
If funds are provided for digital learning, the question is whether students can actually access functioning technology.
If money is allocated to improve school infrastructure, the question is whether the project was completed and whether the facility meets the intended need.
This distinction between allocation and outcome is central to understanding public expenditure.
CAG reports can also encourage greater accountability because their findings are presented through established government and legislative processes. The recent Punjab Composite Audit Report, for example, included a performance audit on the quality of school education and was presented to the state legislature in March 2026.
Ultimately, education spending should be judged not only by the size of the budget but also by the quality and accessibility of services students receive.
No Comment! Be the first one.